
Article
State auditor: Newark schools overstated enrollment, missed millions in savings; matters referred to Criminal Justice
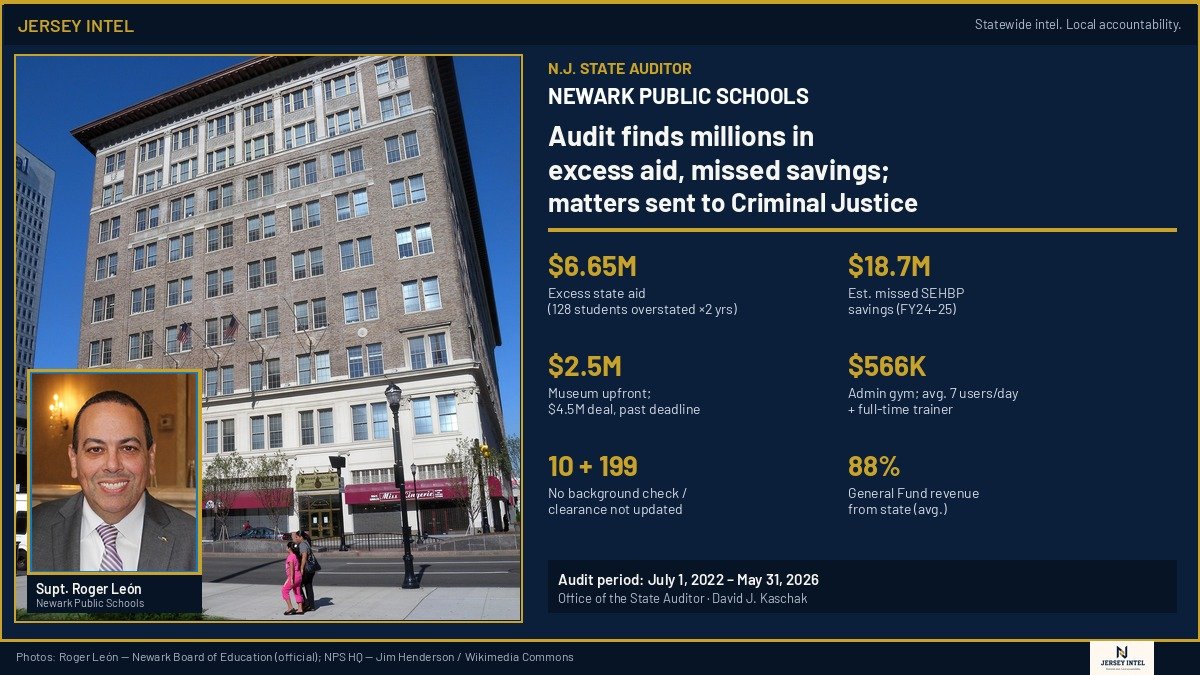
Graphic: Newark Public Schools headquarters with inset of Supt. Roger León and key Office of the State Auditor findings. León photo: Newark Board of Education (official). Building: Jim Henderson / Wikimedia Commons. Data: OSA report 34003524.
- What we know: OSA audited Newark Public Schools for July 1, 2022 through May 31, 2026. Conclusions page states “Certain matters were referred to the state’s Division of Criminal Justice.” Key dollar findings match the auditor’s executive summary and full report (excess ASSA aid $6,654,240; estimated SEHBP savings $18.7 million; museum upfront $2.5 million on a $4.5 million agreement; gym ~$566,000; etc.).
- Why it matters: On average, 88% of the district’s General Fund revenues in the three fiscal years examined came from state appropriations — so documented waste, overpayments, and control failures are a statewide taxpayer story, not only a Newark story.
- What’s next: Watch Division of Criminal Justice action (OSA does not detail what was referred); DOE follow-through on aid recovery and Fun Day reimbursement; district corrective action before the auditor’s planned 2028 compliance review.
A New Jersey Office of the State Auditor performance audit of Newark Public Schools (July 1, 2022–May 31, 2026) documents excess state aid, estimated health-benefits savings foregone, a stalled museum deal, an underused administrative gym, catering and “Fun Day” procurement problems, and incomplete background checks — and says certain matters were referred to the Division of Criminal Justice.
NEWARK / TRENTON — New Jersey’s Office of the State Auditor released a performance audit of Newark Public Schools covering July 1, 2022 through May 31, 2026, finding problems in health benefits, criminal-history screening, state-aid enrollment counts, legal spending, preschool payments, a museum project, an administrative gym, catering, Senior Day trips, and a Central Office “Fun Day.”
In the report’s Conclusions, State Auditor David J. Kaschak writes that tested non-payroll transactions were generally recorded and related to district programs — “However” multiple areas merited management’s attention — and, in a separate line: “Certain matters were referred to the state’s Division of Criminal Justice.”
An X thread by Assemblywoman Dawn Fantasia (R-24) on October 1, 2026 (about 1:05 p.m. ET) listed many of the same dollar figures and linked the official PDFs on pub.njleg.gov. Jersey Intel checked those claims against the primary auditor PDF and library executive summary. The numbers and the Criminal Justice referral check out. Fantasia’s political framing and insults toward the superintendent are her commentary, not findings in the audit.
What the auditor found (primary figures)
Health benefits — estimated $18.7 million. Auditors estimated the district could have saved approximately $18.7 million in fiscal years 2024 and 2025 by participating in the New Jersey School Employees’ Health Benefits Program (SEHBP). Statute and code require districts to examine group options at least every three years and take the most cost-effective plans as a condition of State Aid. The district adopted a self-insured model in January 2022 but did not provide documentation that it completed the required 2025 examination. The $18.7 million figure is an auditor estimate of foregone savings, not a finding that that sum was stolen.
Uncollected contributions — $150,619 + $41,602. The district did not collect required employee health contributions totaling $150,619 and paid ineligible medical and prescription claims totaling $41,602 during unpaid leave. The auditor states the district has not attempted to recover the outstanding contributions, and notes the uncollected amount came from sampling and is likely higher.
ASSA / enrollment — $6.65 million excess aid. Comparing the district’s student information system to 2023 and 2024 Application for State School Aid (ASSA) submissions, auditors found enrollment overstated by 128 students each year. Per the Department of Education, that produced excess State Aid of $6,654,240 for fiscal years 2024 and 2025. Fantasia’s “approximately $6.65 million” matches that DOE figure.
Legal services — $4.7 million above statewide average. Total legal spending exceeded statewide per-pupil averages by a $4.7 million variance over the period reviewed (about $1.6 million per year, or 184%). Districts above 130% of the statewide average per pupil must establish cost-control procedures; auditors said Newark provided none.
Preschool — about $1.3 million. For school year 2023–2024, auditors estimated the district could have saved approximately $1.3 million had it continued enrollment-based payment adjustments when provider enrollment fell below contractual thresholds. The district stopped those adjustments; auditors rejected the idea that NJDOE had directed that stop.
Museum project — $2.5 million upfront; $4.5 million agreement. Under an April 2023 Agreement of Construction, Sale, and Settlement for 15 State Street, the owner was to deliver a “turn-key” museum and administrative offices for a lump-sum $4.5 million. The district paid $2.5 million upfront in May 2023. As of May 2026, the project was about a year past the contractual completion deadline, with little progress and no supporting documentation of construction progress, expenses, or an updated timeline. Auditors found no DOE land-acquisition approval, said the deal circumvented competitive bidding, noted possible additional costs beyond $4.5 million, and said the district missed a $750,000 Department of Community Affairs preservation grant because it neither owned the deed nor held a long-term lease.
Administrative gym — about $566,000. The district spent approximately $566,000 to construct, equip, and operate a gym in a leased administrative building. Construction lacked formal board approval and circumvented competitive bidding. Sign-in sheets (Sept. 16–Dec. 10, 2025) showed an average of seven employees per day, all from the administrative building, with a full-time trainer under a board-approved multi-year management contract. In the auditor’s notes on the district response, OSA states district documents show gym construction/operating/staffing costs came from the General Fund — not a separate “wellness” pot as some district messaging suggested.
Catering — about $1.14 million authorized spend; documentation failures. Over the catering contract window, the district expended approximately $1.14 million. In FY2024 testing, about $184,000 of tested transactions lacked adequate documentation and about $49,000 exceeded meal-pricing limits (possible overlap). Sixteen of 19 catered board meetings exceeded the $10-per-person limit.
Senior Day trips — $711,943. Over fiscal years 2023–2025, Senior Day trips cost $711,943, including carnival booths, DJs/emcees, and karaoke. Auditors said the district did not provide documentation of educational components and that General Fund money paid the bill.
Central Office Staff Fun Day — $57,065. The June 1, 2024 event cost $57,065 via two purchase orders. A board resolution limited spending to $44,000; splitting into two POs circumvented bidding requirements (aggregate over the $44,000 bid threshold). DOE had already directed repayment of $33,649.07 in disallowed State Aid from the first payment; auditors said the State Aid portion of the second payment ($13,251) should likewise be reimbursed.
Background checks — 10 never completed; 199 not updated for Newark. Of 8,043 employees reviewed, 10 never completed required criminal-history background checks (employed 2–27 years). Another 199 who had been cleared for other New Jersey districts had not properly updated clearances for Newark — creating a gap in disqualification notifications. After auditors flagged the issue, nine of the ten completed checks and one separated; most of the 199 then updated.
State share — 88%. On average, 88% of the district’s General Fund revenues were funded by state appropriations in fiscal years 2023–2025.
Doubt angle (required)
- Criminal Justice referral ≠ indictment. The audit confirms a referral. OSA’s own note says the office does not disclose referral details unless the investigative agency allows it. No public charging document is attached to this package. Do not write as if anyone has been charged.
- Performance audit, not a fraud verdict. OSA says tested transactions were generally recorded and related to programs; findings are control, documentation, efficiency, and compliance failures. The “drunk college kid” / board “dozing” language is Fantasia’s rhetoric, not auditor prose.
- $18.7 million is estimated savings, not cash missing from a vault. It assumes SEHBP participation at state rates vs. the district’s self-insured costs. The district may dispute plan design, labor contracts, or network assumptions; OSA did not vouch for counter-numbers in the district response.
- Enrollment overstatement vs. intent. Auditors found ASSA counts did not match the student information system as of the statutory count date. That supports excess aid paid. It does not, by itself, prove criminal intent; that is what a Criminal Justice review would test.
- Museum context is litigation settlement. The $4.5 million deal arose from property-reversion litigation. Weak oversight and missed approvals remain; “vanished museum money” without that context oversimplifies.
- Gym: board approved the management contract. Construction lacked formal board approval and bidding; the $280,440 wellness/fitness management contract was board-approved. Fantasia’s “no board approval” line is accurate for construction, overstated if read as covering the management contract too.
- Fun Day was partly already known. DOE’s $33,649.07 disallowance predates this OSA report; OSA adds the second-payment State Aid piece and procurement framing.
- District response exists. Newark submitted a response (General Counsel Brenda C. Liss cover letter dated September 21, 2026). OSA included auditor’s notes rejecting several district characterizations (gym funding source, preschool COVID framing, bid splitting, etc.). Readers should treat the district’s defenses as contested, not erased.
- Tipster is a partisan elected official. Fantasia is an Assembly Republican and charter-school administrator who says she spent a year pressing the issue. Primary verification does not depend on her; her “I told you so” framing is advocacy.
Bottom line for readers
Verified from the primary State Auditor report: Newark Public Schools was audited for July 2022–May 2026; the report documents the dollar figures Fantasia listed (within ordinary rounding); certain matters were referred to the Division of Criminal Justice; state taxpayers funded most of the General Fund.
Not verified as phrased: That the superintendent “ran the district like a drunk college kid,” that the board was merely “dozing,” or that Criminal Justice has filed charges. Those are opinion or unknown next steps.